Five Strategic Pathways for U.S. Utility Companies Entering the Asia-Pacific Clean Energy Market
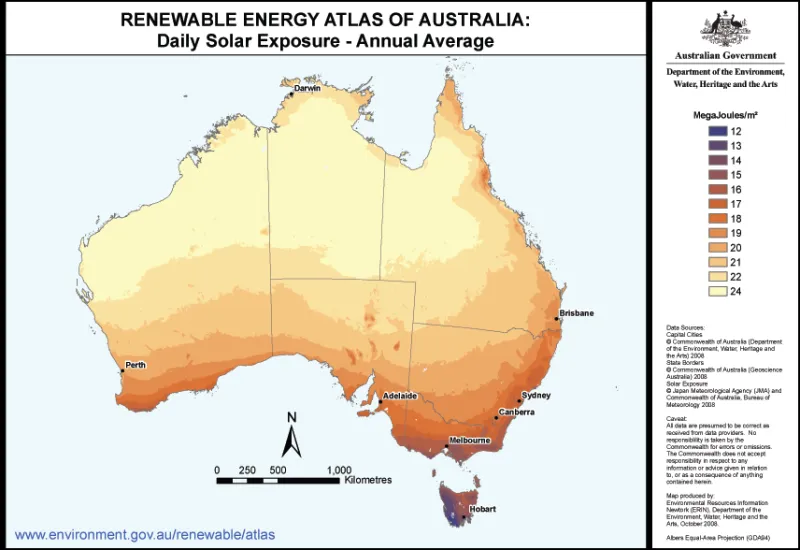
Photo: Australian Government, Geoscience Australia, Japan Meteorological Agency, Bureau of Meteorology, CC BY-SA 4.0, via Wikimedia Commons
A Window of Strategic Opportunity
The Asia-Pacific region is undergoing an energy transformation of remarkable speed and scale. Hong Kong has committed to achieving carbon neutrality by 2050, with interim targets requiring a fundamental reshaping of its electricity generation mix. Singapore is pursuing its Green Plan 2030 with specific mandates around solar deployment, green hydrogen, and regional grid interconnection. Australia, following years of policy uncertainty, has now enacted federal legislation targeting 82% renewable electricity by 2030 — a target that demands an extraordinary volume of new generation, storage, and grid infrastructure.
For American utility companies, this moment represents something genuinely rare: a convergence of market need, regulatory incentive, and competitive white space that invites strategic entry. U.S. firms bring proven capabilities in grid modernization, distributed energy resource management, large-scale renewable development, and utility-scale battery storage — precisely the competencies that Asia-Pacific utilities and governments are actively seeking.
At HK Pacific Utility Consulting, we advise both sides of this equation. The following five pathways represent the most actionable and commercially viable entry strategies available to U.S. utility companies today.
Pathway 1: Technology Licensing and Intellectual Property Agreements
For U.S. companies that have developed proprietary grid management software, demand response platforms, or advanced metering infrastructure, technology licensing offers a low-capital, high-margin entry point into Asia-Pacific markets.
Hong Kong's two major power utilities — both of which operate under Scheme of Control agreements requiring continuous capital investment and efficiency improvement — have active procurement programs for grid modernization technologies. Singapore's SP Group, the national grid operator, has similarly demonstrated appetite for advanced distribution management systems and smart grid analytics platforms developed by U.S. firms.
The licensing model is particularly well-suited to companies that wish to establish a regional presence without assuming the operational and regulatory responsibilities of a local utility license. Properly structured, an intellectual property licensing arrangement can generate recurring revenue, establish brand recognition in the market, and create a foundation for deeper commercial relationships over time. U.S. companies pursuing this pathway should ensure that licensing agreements include clear provisions for adaptation to local regulatory standards, as grid architecture and communication protocols in Asia-Pacific markets differ in meaningful ways from North American norms.
Pathway 2: Joint Ventures with Established Regional Utilities
For companies prepared to commit more substantial capital and organizational resources, joint ventures with established Asia-Pacific utility operators offer accelerated market entry with significantly reduced regulatory and operational risk.
The joint venture model has a proven track record in the region. Several of Australia's largest renewable energy projects have been developed through partnerships between international energy companies and domestic utilities, with the local partner providing regulatory relationships, grid connection expertise, and community stakeholder management while the international partner contributes capital, technology, and development experience.
In Hong Kong, the regulatory structure creates specific opportunities for joint development of off-grid renewable assets — particularly offshore wind, where the government has issued development zones and is actively seeking experienced international developers to partner with local entities. A U.S. company with offshore wind development experience in markets such as the Northeast U.S. or the Gulf of Mexico would carry meaningful credibility in these conversations.
When structuring joint ventures in this region, governance clarity is paramount. U.S. corporate development teams should prioritize clear decision-making protocols, defined exit mechanisms, and explicit alignment on environmental, social, and governance commitments — the latter being an area of increasing scrutiny from both regional regulators and international capital providers.
Pathway 3: Green Hydrogen and Emerging Technology Development Agreements
Green hydrogen has emerged as a central pillar of Asia-Pacific decarbonization strategy, and it represents a domain where U.S. technological leadership is both recognized and actively sought. Singapore has established itself as a regional hub for green hydrogen import and blending, with the government issuing calls for proposals from international technology providers. Australia, with its exceptional renewable resource endowment, is positioning itself as a major green hydrogen exporter, with projects targeting Japanese, Korean, and potentially Hong Kong and Singaporean offtake.
U.S. companies with expertise in electrolyzer technology, hydrogen storage systems, or ammonia conversion processes are well-positioned to enter the region through development agreements tied to specific project pipelines. These arrangements typically involve a combination of technology provision, project development services, and equity co-investment, structured to align incentives across the development timeline.
The regulatory environment for green hydrogen in the Asia-Pacific is still maturing, which creates both risk and opportunity. Companies that engage early — contributing to standards development and regulatory consultation processes — will be better positioned to shape frameworks that reflect their technological capabilities.
Pathway 4: Distributed Energy and Microgrid Solutions for Commercial and Industrial Clients
Not all Asia-Pacific energy market entry requires engagement with large utilities or government regulators. The commercial and industrial distributed energy segment — encompassing rooftop solar, battery storage, demand management, and behind-the-meter optimization — is growing rapidly across the region and is accessible to U.S. companies through direct commercial relationships.
Hong Kong's commercial real estate sector, one of the densest and most energy-intensive in the world, is under increasing pressure from both regulatory mandates and tenant sustainability commitments to reduce carbon intensity. U.S. companies offering integrated energy-as-a-service models — in which the provider finances, installs, operates, and maintains distributed energy systems under long-term performance contracts — have found receptive audiences among Hong Kong and Singapore property developers and real estate investment trusts.
This pathway requires relatively modest regulatory engagement compared to grid-scale utility development, and it allows U.S. firms to build regional operational experience, local staff capacity, and customer relationships that can support more ambitious market entry strategies over time.
Pathway 5: Advisory and Engineering Services for Utility Modernization Programs
For U.S. utility holding companies with engineering subsidiaries, consultancies, or professional services divisions, the Asia-Pacific utility modernization wave presents a substantial services market opportunity that does not require equity investment or operational licenses.
Government-owned utilities across the region — including those in less-developed Asia-Pacific markets that look to Hong Kong and Singapore as regional benchmarks — are investing heavily in grid resilience, cybersecurity, asset management systems, and workforce capability development. American engineering and consulting firms bring internationally recognized expertise in these domains, and the U.S. government's clean energy diplomacy initiatives have created favorable conditions for commercial relationships to follow.
Engagement through this pathway is often facilitated by participation in industry forums, bilateral trade missions, and multilateral development bank procurement processes — channels that HK Pacific Utility Consulting actively monitors and supports on behalf of our U.S. clients.
The Strategic Imperative
The Asia-Pacific clean energy transition will require trillions of dollars in investment and an enormous transfer of technology and operational expertise over the coming two decades. American utility companies that engage strategically now — through licensing, joint ventures, technology development, distributed energy services, or professional advisory relationships — will be positioned to capture durable commercial value while contributing meaningfully to one of the world's most consequential infrastructure transformations.
The pathways described here are not theoretical. They reflect the actual deal structures, regulatory frameworks, and partnership models that are actively being pursued across the region today. The question for U.S. corporate development teams is not whether the opportunity exists — it is whether their organizations are prepared to act on it with the seriousness and regional fluency it demands.