Selling Shovels in the Solar Gold Rush: Where US Firms Can Win Asia-Pacific's Distributed Energy Buildout Without Buying a Single Panel
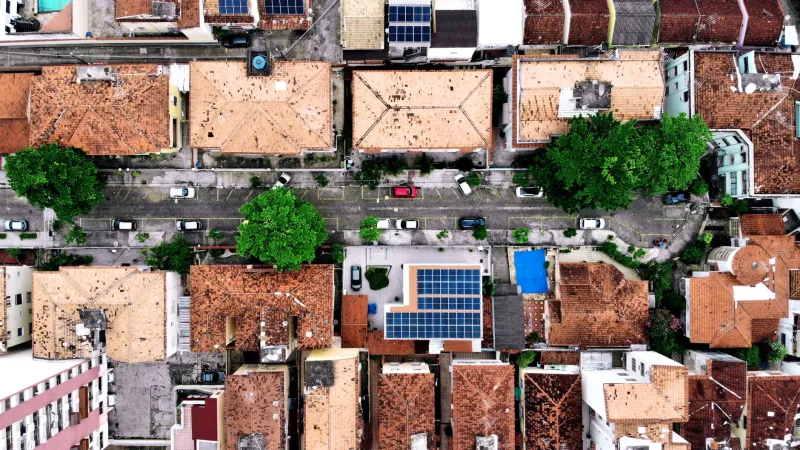
American capital has a predictable instinct when it encounters a boom: buy the asset. It happened with data centers, it happened with pipelines, and it is happening now with distributed energy across the Asia-Pacific region. US investors are circulating term sheets for rooftop solar portfolios in Australia, community battery schemes in Japan, and utility-scale aggregations across Southeast Asia — all while the faster, more durable opportunity accumulates quietly in a layer most asset-focused players never examine.
That layer is services. And for American firms — particularly consultancies, software vendors, and engineering specialists — it may be the most accessible entry point into Asia-Pacific energy markets currently available.
The Asset Play Everyone Is Making
The numbers explain the fixation. Australia leads the world in residential rooftop solar penetration, with more than one in three suitable dwellings generating power. Japan's post-Fukushima energy reforms unleashed a distributed generation wave that shows no sign of slowing. Vietnam, the Philippines, and Thailand are layering feed-in tariffs and net metering schemes atop rapidly growing electricity demand.
Asset ownership in these markets, however, carries familiar burdens: foreign ownership restrictions, currency exposure, long payback periods, and the political risk that accompanies any physical footprint in a foreign jurisdiction. These are the very frictions this publication has examined repeatedly — and they apply with full force to distributed assets, which are smaller, more numerous, and administratively heavier than their utility-scale counterparts.
Services businesses invert that risk profile. Revenue is contractual rather than collateralized by physical assets. Capital requirements are modest. And critically, the demand for these services is growing faster than the assets themselves, because every new panel, battery, and meter multiplies the complexity that someone must manage.
Four Niches Where Americans Hold a Genuine Edge
Grid orchestration software. Millions of distributed resources create coordination problems that legacy utilities cannot solve with spreadsheets. Virtual power plant platforms, DERMS (distributed energy resource management systems), and forecasting engines built for the competitive US market — think of the software ecosystems that grew up around Texas's ERCOT market or California's behind-the-meter boom — are technically mature and exportable. Japanese and Australian utilities are actively procuring in this category.
Advanced metering and data analytics. Southeast Asian markets are mid-transition to smart metering, and the data infrastructure requirements are enormous. US firms with metering analytics, cybersecurity, and billing-integration expertise are well positioned, particularly where English-language business environments — Singapore, the Philippines, Australia — lower the barrier to entry.
Demand response and flexibility markets. Australia's Wholesale Demand Response Mechanism and Japan's emerging balancing markets are creating monetization channels that require aggregation expertise. American firms that cut their teeth on PJM's demand response programs carry directly transferable knowledge.
O&M and asset performance. Somebody must service a rooftop system in suburban Brisbane or a community battery in Osaka. Operations and maintenance is unglamorous, contract-based, and — because it requires local labor partnerships — naturally suited to joint venture structures rather than outright ownership.
The Regulatory Reality Check
Enthusiasm, however, must survive contact with the regulatory map. Not every Asia-Pacific market permits foreign service providers to compete, and the distinctions are frequently counterintuitive.
Before committing resources, US firms should work through a disciplined checklist:
- Licensing path: Does the market require a local utility license to sell energy services, or is an ESCO (energy services company) registration sufficient? Singapore's liberalized retail market is comparatively open; Indonesia's framework remains dominated by PLN.
- Foreign ownership caps: Do equity restrictions apply to service businesses, or only to generation? Vietnam's service-sector ceilings differ materially from its generation rules.
- Data localization: Can grid and customer data leave the country? Japan and Australia impose few restrictions; others effectively require in-country hosting, which shapes partnership structures.
- Grid access rules for third parties: Can an independent aggregator bid into the wholesale or balancing market, or is that reserved for incumbent utilities? Australia's answer is yes; several ASEAN markets remain closed.
- Local partnership requirements: Is a domestic joint venture mandatory, advisable, or optional? The answer determines whether your market entry is a licensing exercise or a courtship.
A market that fails two or more of these tests is not necessarily off-limits — but it changes the optimal structure from direct entry to partnership, licensing, or technology transfer.
The Recurring Revenue Advantage
The financial logic deserves emphasis. A distributed solar asset might yield a mid-single-digit return, leveraged, over a twenty-five-year hold. A software or services contract in the same market can produce gross margins above sixty percent, renewable annually, with no currency-hedged asset base on the balance sheet. For US firms accustomed to the annuity economics of utility services at home — the model perfected by American metering, engineering, and grid-services firms over decades — this is a familiar playbook applied to an unfamiliar geography.
The window matters, too. Distributed energy buildouts across the region are accelerating now, and the service relationships formed during initial deployment tend to persist. Firms that establish beachheads in the next three to five years will inherit renewal streams that later entrants will find expensive to displace.
Positioning for the Layer Beneath
The American instinct to own the asset is not wrong — it is simply incomplete. The distributed energy transition across Japan, Australia, and Southeast Asia is generating a services economy that grows with every installation, compounds with every regulatory opening, and rewards exactly the capabilities — software, analytics, program management, technical consulting — that US firms have spent decades refining.
The gold rush is real. But history's most reliable returns have gone to those selling the shovels. In Asia-Pacific's distributed energy boom, the shovels are contracts, platforms, and expertise — and the market for them is only beginning to open.