When High Yields Become Warning Signs: Rethinking Asia-Pacific Utility Dividends Through a Capital Expenditure Lens
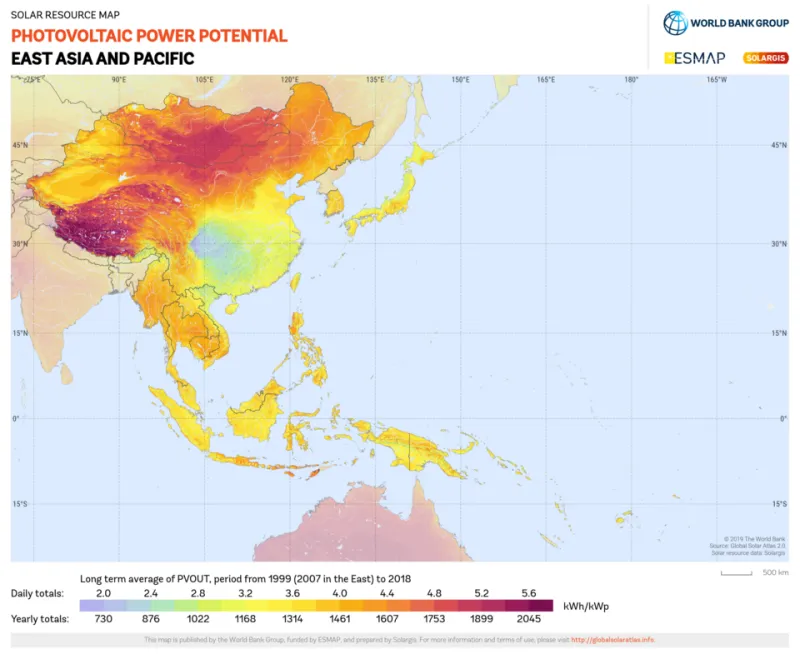
Photo: Solargis, CC BY 4.0, via Wikimedia Commons
The Allure of the Asia-Pacific Yield Story
For U.S. institutional investors and income-focused portfolio managers, the Asia-Pacific utility sector has long presented a compelling surface narrative: regulated cash flows, quasi-monopolistic market positions, and dividend yields that routinely outpace what domestic utility peers can offer in an era of compressed returns. On paper, the proposition looks straightforward. In practice, it demands considerably more scrutiny.
Over the past several years, a subset of utilities operating across Hong Kong, Singapore, and Australia have maintained payout ratios that, by any conventional measure, appear generous. Some exceed 80 percent of earnings. Others approach or surpass free cash flow generation entirely. For a U.S. investor accustomed to evaluating domestic utilities — where dividend sustainability is typically benchmarked against a disciplined capital reinvestment cycle — these figures should prompt questions rather than enthusiasm.
The central issue is not that high dividends are inherently problematic. It is that high dividends, when sustained at the expense of capital reinvestment, create a compounding liability that regulators, grid operators, and ultimately shareholders will eventually be forced to reckon with.
What Payout Ratios Don't Tell You
Payout ratio analysis, as commonly applied by U.S. equity research teams, tends to treat dividend coverage in isolation. A utility earning $1.00 per share and paying $0.85 in dividends registers as aggressive but manageable. What this framing misses is the capex context — specifically, whether the remaining $0.15 is being deployed meaningfully toward grid hardening, asset replacement, or climate adaptation infrastructure.
Across several mid-tier Australian electricity distributors, for instance, the past decade has seen a pattern of elevated shareholder distributions running concurrently with deferred network investment. Regulatory determinations from the Australian Energy Regulator have, in multiple cases, flagged asset condition concerns and compelled utilities to accelerate spending programs that had been quietly postponed. The consequence for investors was not a windfall — it was a reset of the financial model, with higher capex requirements compressing the very distributions that had made the stocks attractive in the first place.
Singapore presents a somewhat different dynamic. The city-state's highly centralized regulatory framework under the Energy Market Authority imposes strict performance standards, and utilities operating there face meaningful financial penalties for reliability failures. When a utility has been distributing capital that should have been directed toward network resilience, the first major weather event or equipment failure does not merely create an operational disruption — it triggers a regulatory response that can reset the earnings trajectory for multiple fiscal years.
Hong Kong's Infrastructure Accounting Problem
Hong Kong occupies a particularly instructive position in this analysis. The territory's two major power companies operate under a Scheme of Control arrangement that links permitted returns to a fixed asset base. In theory, this structure incentivizes investment — higher capex means a larger asset base, which supports a larger permitted return. In practice, the relationship between capex commitments and actual grid modernization has been uneven.
U.S. investors evaluating Hong Kong utility exposure through a pure yield lens frequently overlook the extent to which permitted return structures can mask underlying asset deterioration. A utility earning its allowed return on a partially depreciated, aging asset base is not the same financial proposition as one earning that return on a modernized, climate-resilient network. The former carries stranded asset risk; the latter represents durable infrastructure value. From the outside, both may look identical on a dividend yield screen.
Furthermore, Hong Kong's increasing exposure to extreme weather events — including the intensifying typhoon seasons that have stressed grid infrastructure in recent years — raises legitimate questions about whether historical capex levels are adequate preparation for the climate volatility that climatologists project for the region through mid-century. Utilities that have prioritized distribution over resilience investment are, in effect, borrowing against their own future reliability.
The Stranded Asset Dimension
Beyond deferred maintenance, the energy transition introduces a second layer of capital risk that high-payout utilities may be systematically underweighting. Across the Asia-Pacific region, the pace of renewable energy integration varies considerably by jurisdiction, but the directional pressure is consistent: legacy thermal generation assets face an accelerating obsolescence timeline.
For utilities that have been returning capital to shareholders rather than repositioning their generation portfolios, the transition creates a compounding problem. Not only are they entering the decarbonization era with aging conventional assets, they are doing so with balance sheets that have been progressively depleted by distributions that outpaced genuine earnings power. When regulatory mandates or carbon pricing mechanisms force accelerated asset retirement, the capital required for replacement must come from somewhere — and if the dividend has been consuming that capital for years, the options narrow quickly.
Australian utilities navigating the National Electricity Market's evolving capacity mechanisms offer a preview of this dynamic. Several have faced the dual challenge of managing stranded coal and gas assets while simultaneously funding renewable build-outs, all against a backdrop of shareholder expectations that were calibrated to the high-yield era. The resulting financial tension has, in several cases, produced exactly the dividend reductions that yield-focused U.S. investors were most hoping to avoid.
A Framework for More Disciplined Evaluation
None of this is to suggest that Asia-Pacific utility dividends are categorically unreliable or that the sector lacks genuine investment merit. Rather, the argument is that U.S. investors applying domestic analytical frameworks to these markets without accounting for regional capex dynamics, regulatory architecture, and climate exposure are accepting risks they may not have fully priced.
A more rigorous evaluation approach would integrate several additional data points alongside conventional yield and payout ratio metrics. First, a utility's capex-to-depreciation ratio over a trailing five-year period provides a meaningful signal about whether asset reinvestment is keeping pace with asset consumption. Ratios persistently below 1.0 warrant careful scrutiny. Second, regulatory history — including any findings, penalty assessments, or mandated investment programs — offers direct evidence of how a utility has managed the tension between shareholder distributions and infrastructure obligations. Third, climate scenario analysis, while still nascent in many Asia-Pacific regulatory disclosures, is increasingly available through third-party research and should inform any long-duration capital commitment.
The Discipline the Market Rarely Rewards
There is an inherent asymmetry in how markets respond to utility dividend policy. Announcing a distribution increase generates immediate positive market reaction; disclosing an accelerated capex program typically does not, even when the latter represents the more financially sound decision. This dynamic creates persistent pressure on utility management teams to prioritize near-term shareholder returns over long-cycle infrastructure investment — and it creates a corresponding obligation for sophisticated investors to look past the headline yield figure.
At HK Pacific Utility Consulting, our advisory work consistently reinforces a single core principle: the most durable Asia-Pacific utility investments are those where dividend policy is a reflection of genuine financial strength, not a substitute for it. For U.S. investors building exposure to this region, the discipline to distinguish between the two is not merely analytically useful — it is essential to avoiding the yield traps that have caught more than a few institutional portfolios off guard.