Closing the Capital Chasm: Why US Utility Investors Hold the Key to Asia-Pacific's Renewable Financing Crisis
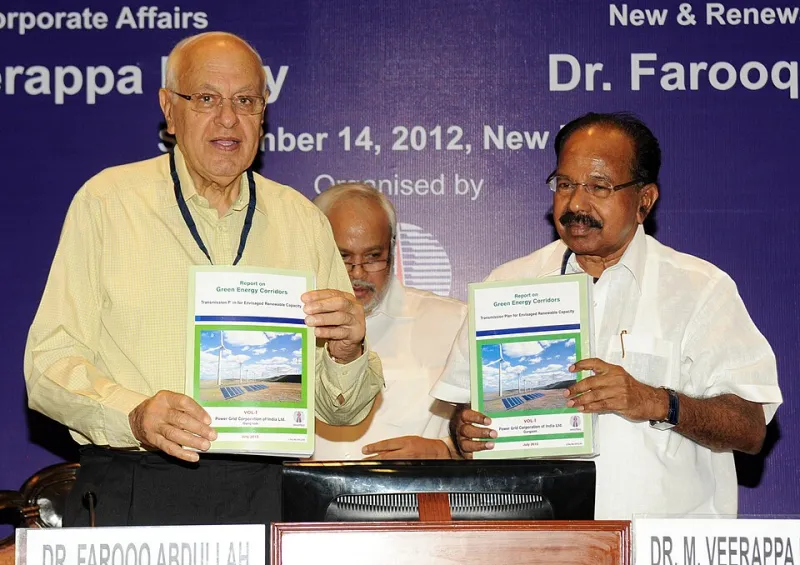
Photo: Ministry of New and Renewable Energy, Government of India, GODL-India, via Wikimedia Commons
The Scale of the Problem No One Is Talking About Loudly Enough
The numbers are staggering, and yet they still fail to fully convey the urgency. According to estimates from the Asian Development Bank, the Asia-Pacific region requires approximately $1.7 trillion in annual infrastructure investment through 2030 — a significant portion of which is earmarked for clean energy generation, grid modernization, and transmission expansion. Domestic capital markets across most of the region are simply not equipped to absorb that demand alone.
This is not a story about developing economies struggling to attract investment. It is a story about structural misalignment — between the long-duration capital that energy infrastructure requires and the short-term liquidity preferences of regional banks, between the risk appetites of local institutional investors and the risk profiles of greenfield renewable projects, and between the regulatory certainty that sophisticated investors demand and the policy environments that many Asia-Pacific governments currently provide.
For US utility companies and their financial partners, this misalignment is not a warning sign. It is an entry point.
Why US Utilities Are Uniquely Positioned
American utility companies have spent the better part of two decades navigating their own energy transition at home. They have developed proprietary expertise in utility-scale solar and wind procurement, in managing stranded asset liabilities, in structuring power purchase agreements that satisfy both regulators and capital markets, and in deploying grid modernization technology at scale. That experience is not replicable quickly, and it is precisely what most Asia-Pacific markets currently lack.
Beyond operational know-how, US utilities bring something equally valuable: credibility with institutional capital. A US-led project consortium pursuing a 500-megawatt offshore wind development in Vietnam or a grid digitization initiative in the Philippines carries a financing pedigree that dramatically lowers the cost of capital for the entire project. International Development Finance Corporation (DFC) support, Export-Import Bank co-lending facilities, and green bond issuances structured under US regulatory frameworks all become accessible when American sponsors are at the table.
This is not theoretical. US-backed consortia have successfully deployed blended finance structures in Indonesia's geothermal sector and in utility-scale battery storage projects across Southeast Asia, using first-loss capital from development finance institutions to crowd in commercial lenders who would otherwise have remained on the sidelines.
Financing Structures That Actually Work Across Jurisdictions
One of the most persistent mistakes US investors make when approaching Asia-Pacific energy projects is importing financing structures wholesale from their domestic experience. Project finance models that work cleanly in Texas or California often encounter serious friction when applied to markets with limited offtake creditworthiness, underdeveloped hedging instruments, or inconsistent enforcement of contractual rights.
Several adapted structures have demonstrated resilience across a range of Asia-Pacific regulatory environments.
Blended finance with DFI anchor capital remains the most reliable mechanism for de-risking greenfield projects in frontier and emerging markets. By pairing DFC or World Bank Group first-loss tranches with commercial debt and equity from US utility sponsors, project developers can achieve investment-grade blended ratings that would otherwise be unattainable. This structure has been particularly effective in markets like Bangladesh and Sri Lanka, where sovereign creditworthiness constrains the financing options available to state-owned offtakers.
Green bond issuances denominated in US dollars have gained significant traction as a mechanism for repatriating capital to American investors while funding local renewable development. Hong Kong's status as a regional capital markets hub makes it an ideal issuance venue, offering access to both Asian institutional buyers and US-listed bond indices.
Contractual ring-fencing through special purpose vehicles domiciled in neutral jurisdictions — Singapore and Hong Kong being the most common choices — provides US investors with a layer of legal predictability that direct investment in local project companies cannot guarantee. This structure also facilitates exit via secondary market sales to regional infrastructure funds, preserving liquidity optionality.
Project Opportunities Worth Watching Now
Several near-term opportunities stand out for US utility investors who are prepared to move with strategic deliberation rather than reactive speed.
Australia's regulated network businesses are undergoing substantial capital expenditure cycles driven by the retirement of coal-fired generation and the need to integrate distributed energy resources. For US utilities already familiar with regulated asset base models, Australian network investments offer a familiar risk profile with meaningful yield premiums over comparable domestic assets.
The Philippines' open access and retail competition framework, now maturing after years of partial implementation, is creating genuine private sector openings in distribution modernization and renewable capacity addition. US utilities with smart grid technology portfolios are particularly well-positioned to pursue integrated investment and technology licensing arrangements.
Japan's offshore wind auction program, while administratively complex, represents one of the largest single concentrations of investable renewable capacity in the Asia-Pacific region. US developers who have navigated the Jones Act and federal permitting processes for domestic offshore wind will find the Japanese regulatory learning curve steep but manageable.
A Strategic Imperative, Not an Opportunistic Trade
The financing gap in Asia-Pacific's energy transition will not remain unfilled indefinitely. European utilities, Japanese trading houses, and increasingly well-capitalized regional developers are all competing for the same project pipelines. The window during which US investors can establish first-mover advantages in key markets is measurable in years, not decades.
What distinguishes successful US entrants from those who circle the opportunity without committing is not financial capacity — it is market intelligence. Understanding the specific regulatory architectures, the creditworthiness of state-owned offtakers, the currency hedging options available in each jurisdiction, and the political dynamics that shape tariff-setting processes requires sustained regional engagement, not periodic due diligence exercises.
For US utility companies prepared to build that knowledge base, Asia-Pacific's capital chasm is among the most compelling infrastructure investment opportunities available anywhere in the world today.