Hong Kong's Infrastructure Crossroads: Why American Grid Tech Companies Should Be Paying Close Attention Right Now
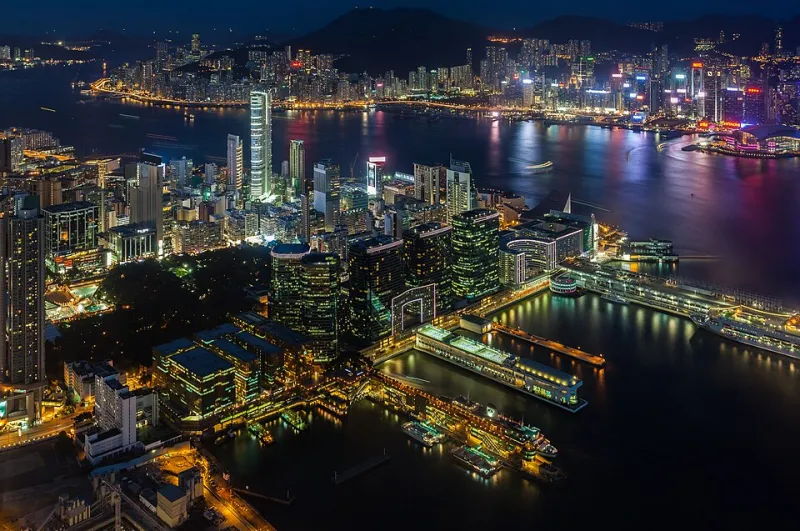
Photo: Diego Delso, CC BY-SA 3.0, via Wikimedia Commons
There is a particular kind of market opportunity that announces itself quietly, through engineering reports and utility commission filings rather than press releases and trade show keynotes. Hong Kong's infrastructure modernization cycle is precisely that kind of opportunity — and for American technology companies operating in the grid modernization, smart metering, and industrial IoT spaces, the signals have been accumulating long enough to warrant a serious strategic response.
The territory's two primary electricity providers, CLP Power and HK Electric, operate networks that, while reliably maintained, carry the structural weight of decades-old design assumptions. Substations commissioned in the 1970s and 1980s, distribution architecture that predates smart grid concepts by a generation, and metering infrastructure that lacks the two-way communication capabilities now considered baseline in modernized Western grids — these are not hypothetical vulnerabilities. They are documented characteristics of a system that its own operators acknowledge must evolve.
The Infrastructure Timeline: What Is Coming and When
Understanding the opportunity requires understanding the rhythm of Hong Kong's utility investment cycle. Unlike U.S. investor-owned utilities, which file integrated resource plans and rate cases on publicly accessible dockets, Hong Kong's utility regulatory framework operates through Scheme of Control Agreements (SCAs) — long-term performance-based arrangements between the government and each of the two franchised electricity companies.
CLP Power's current SCA framework and HK Electric's equivalent arrangement both embed capital expenditure incentives that reward investment in reliability improvement and emissions reduction. The Hong Kong government's Climate Action Plan 2050, published in 2021, set explicit decarbonization targets for the electricity sector — moving away from coal, expanding natural gas, and integrating renewable sources — that cannot be achieved without substantial grid infrastructure upgrades.
The practical consequence is a multi-year capital deployment cycle that is already underway. Smart metering rollout programs, substation automation projects, and distribution management system upgrades are moving from planning phases into procurement. Industry observers tracking CLP Power's published capital expenditure disclosures note consistent increases in grid modernization line items over the past several reporting periods. For American vendors, the question is not whether this spending will happen — it is whether they will be positioned to compete for it when it does.
Why Hong Kong Functions as a Regional Technology Proving Ground
The strategic calculus for U.S. technology companies extends well beyond Hong Kong's domestic market, which, at roughly 7.5 million people, would not independently justify the market entry investment required. The more compelling logic is geographic and reputational.
Hong Kong occupies a singular position in the Asia-Pacific technology adoption ecosystem. Its regulatory environment, while distinct from the U.S. system, operates with a degree of transparency and institutional consistency that gives technology vendors a reliable testing environment. Its utility operators are sophisticated buyers with international procurement experience and a demonstrated willingness to engage with foreign technology providers when the value proposition is clear.
Perhaps most importantly, a successful deployment in Hong Kong generates the kind of reference case that carries weight in procurement conversations across the broader region. Utility decision-makers in Singapore, Taiwan, and increasingly in Southeast Asian markets where grid modernization investment is accelerating look to Hong Kong implementations as validation signals. A smart grid management system or advanced metering infrastructure platform that has been deployed at scale in Hong Kong arrives in the next market with a credibility premium that no amount of trade show marketing can replicate.
This dynamic is well understood by European and Japanese technology vendors, many of whom have pursued Hong Kong engagements specifically for their regional reference value. American companies that have been slower to recognize this logic are, in some cases, ceding ground that will be difficult to recover.
Identifying the Decision-Makers and Procurement Pathways
For U.S. companies unfamiliar with Hong Kong's utility procurement landscape, the path from market interest to contract award is less opaque than it might initially appear — but it does require deliberate navigation.
At the utility level, CLP Power and HK Electric each maintain distinct procurement functions with technology evaluation processes that blend international competitive tendering with long-term vendor relationship management. For major infrastructure technology categories — distribution automation, metering data management, grid analytics platforms — the evaluation cycles are long, often spanning eighteen to thirty-six months from initial technical engagement to contract execution. Early-stage technical dialogue, facilitated through formal vendor qualification processes or industry working groups, is not optional. It is the mechanism through which evaluation criteria are shaped.
At the government level, the Electrical and Mechanical Services Department (EMSD) plays a regulatory and technical oversight role that makes it a critical stakeholder for any technology with grid safety or interoperability implications. U.S. companies accustomed to engaging with NERC or state PUCs will find the EMSD's technical rigor familiar, even if the procedural format differs.
Industry associations, including the Hong Kong Electrical & Mechanical Industries Training Board and various smart city working groups convened under the Innovation and Technology Bureau, provide structured forums for technology introductions that carry more weight than cold outreach. For American companies without established Hong Kong presence, these forums represent the most efficient initial point of engagement.
The Smart City Connection: Expanding the Aperture
It would be a strategic error to frame this opportunity purely in traditional utility terms. Hong Kong's Smart City Blueprint, now in its second iteration, explicitly integrates utility infrastructure modernization with broader urban digitization objectives — smart traffic management, building energy management, water network monitoring, and emergency services coordination. The electricity grid, in this framework, is not merely a power delivery system. It is a data infrastructure layer.
For American IoT and data analytics companies, this framing opens procurement channels beyond the two franchised utilities. The Hong Kong Housing Authority, which manages one of the world's largest public housing portfolios, is actively pursuing building-level energy management deployments. The MTR Corporation, which operates the territory's mass transit network and has significant property development interests, represents another sophisticated buyer with appetite for grid-edge technology.
Positioning for the Window
The infrastructure modernization cycle underway in Hong Kong will not wait indefinitely for American companies to complete their market entry deliberations. Vendor qualification processes have lead times. Reference relationship development requires sustained engagement. The firms that arrive having already invested in technical localization, regulatory familiarity, and stakeholder relationships will compete on merit. Those that arrive late will compete on price — a considerably less favorable position.
For U.S. grid technology companies evaluating international expansion priorities, Hong Kong deserves a place near the top of the list — not because it is the largest market available, but because it is the right market at the right moment, with consequences that extend far beyond its own borders.