Fractured Rules, Hidden Gains: A U.S. Utility's Guide to Regulatory Divergence Across Asia-Pacific
Photo: East Asia and Pacific Media Hub U.S. Department of State, Public domain, via Wikimedia Commons
For most American utility executives, the phrase "regulatory complexity" conjures images of FERC proceedings and state PUC dockets. But spend any time studying the Asia-Pacific energy landscape, and a different kind of complexity emerges — one that is less about bureaucratic friction and more about structural opportunity. Across fourteen-plus distinct regulatory environments, the region presents a mosaic of standards, approval timelines, and compliance thresholds that vary so dramatically from one market to the next that firms capable of navigating them hold a genuine first-mover advantage.
This is the core premise of regulatory arbitrage in the Asia-Pacific context: the gap between what different jurisdictions require, permit, or restrict creates asymmetries that strategically agile companies can exploit — legally and profitably.
Understanding the Landscape: Why Standards Diverge So Sharply
The Asia-Pacific region was never designed with harmonization in mind. Unlike the European Union, which has spent decades aligning energy directives across member states, ASEAN and its neighboring economies developed their utility sectors largely in isolation, shaped by colonial-era infrastructure legacies, distinct development trajectories, and varying degrees of market liberalization.
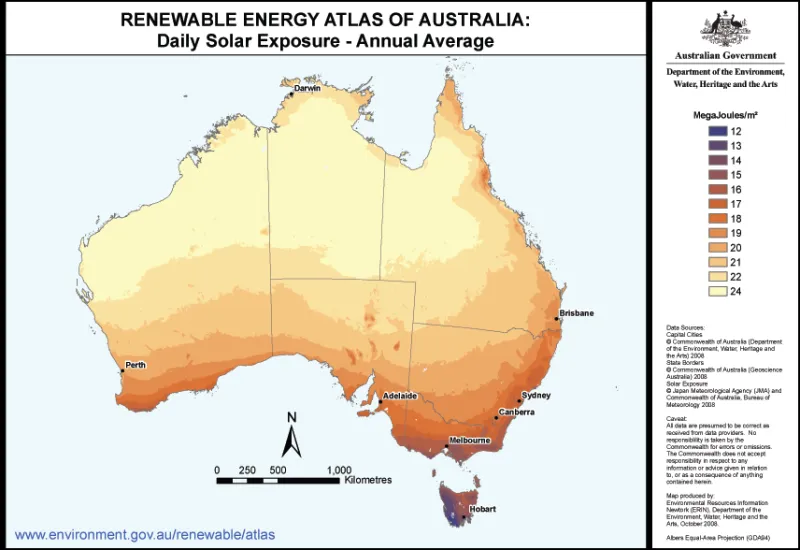
Consider the contrast between Australia and Indonesia. Australia operates one of the world's most sophisticated national electricity markets, with carbon reporting obligations, competitive wholesale pricing, and an independent market operator modeled in part on Western deregulated structures familiar to U.S. firms operating in PJM or ERCOT. Indonesia, by contrast, maintains a state-dominated framework through PLN, its national utility, where independent power producers must navigate bilateral negotiations rather than transparent market mechanisms.
Japan presents yet another configuration. Post-Fukushima reforms introduced retail competition and separated transmission from generation, but the country's grid frequency split — 50 Hz in the east, 60 Hz in the west — creates technical compliance requirements that have no parallel in U.S. experience and demand specialized engineering adaptation.
For a U.S. company entering this region, these divergences are not merely logistical headaches. They are signals about where barriers to entry are highest — and, consequently, where competitive moats are deepest for those who clear them.
Case Study: Emissions Reporting as a Competitive Wedge
One of the clearest examples of actionable regulatory arbitrage involves emissions disclosure standards. In markets such as South Korea and Singapore, mandatory carbon reporting for large energy consumers and producers has become increasingly rigorous, moving toward alignment with international frameworks like the Task Force on Climate-related Financial Disclosures (TCFD). Meanwhile, several Southeast Asian markets — including Thailand and the Philippines — still rely on voluntary or sector-specific reporting regimes that lack consistent enforcement.
American utility companies with established ESG compliance infrastructure — built to satisfy SEC disclosure expectations and investor relations requirements — arrive in these markets with documentation systems, internal audit protocols, and reporting workflows that local competitors simply do not possess at the same level of maturity.
In practical terms, this means a U.S. firm bidding on a joint venture or concession agreement in Singapore can present a compliance portfolio that signals institutional credibility to both regulators and local financial partners. In markets transitioning toward stricter standards, that credibility is bankable. It shortens due diligence timelines, reduces bonding requirements in some cases, and positions the American partner as the de facto compliance anchor in a consortium.
Navigating Multi-Jurisdictional Approval Simultaneously
Perhaps the most underestimated operational challenge for U.S. utilities pursuing regional expansion is the concurrent management of approval processes across multiple jurisdictions. A company pursuing projects in Vietnam, Malaysia, and the Philippines simultaneously faces three separate environmental impact assessment frameworks, three sets of grid connection standards, and three distinct foreign investment review processes — all running on different clocks.
The firms that succeed here share a common structural trait: they do not treat each market as a standalone project. Instead, they build what might be called a regulatory operations layer — a dedicated internal team or retained advisory structure capable of mapping approval dependencies, identifying which permits in one country can be templated from work already completed in another, and flagging where a regulatory decision in one market sets a precedent that can be cited in another.
For instance, an interconnection study completed to Australian Energy Market Operator (AEMO) standards carries technical credibility that can accelerate equivalent reviews in New Zealand and, increasingly, in parts of Southeast Asia where regulators are benchmarking against developed-market frameworks. Documenting this transferability is not automatic — it requires deliberate regulatory intelligence work — but the time savings are measurable.
Building the Framework: Four Practical Principles
For U.S. utility companies ready to treat regulatory divergence as a strategic input rather than a compliance burden, the following principles provide a workable foundation.
Map standards before mapping markets. Before evaluating a country's demand profile or tariff structure, conduct a regulatory baseline assessment. Identify which standards align with U.S. domestic experience, which require material adaptation, and which represent genuine barriers that competitors are unlikely to clear quickly.
Sequence entry by compliance transferability. Enter markets where your existing compliance infrastructure provides the greatest lift first. Establish operational credibility, build local regulatory relationships, and generate case studies before moving into jurisdictions with higher adaptation costs.
Treat local regulatory counsel as a strategic partner, not a vendor. In markets like Japan and South Korea, the relationship between a company and its regulatory advisors is often as important as the technical merits of a project proposal. Invest in long-term retained relationships rather than transactional engagements.
Monitor harmonization signals actively. The Asia-Pacific region is not static. ASEAN is incrementally advancing its energy connectivity agenda, and bilateral agreements between major economies continue to reshape the regulatory terrain. Companies that track these developments early can position themselves ahead of the next wave of market opening.
The Compliance Advantage Is Time-Limited
It would be a mistake to assume that the regulatory gaps described here will persist indefinitely. As Asia-Pacific markets mature and international capital flows demand greater standardization, the divergence that currently creates arbitrage opportunities will narrow. The window for U.S. utility companies to leverage their compliance sophistication as a genuine differentiator is real — but it is not permanent.
The firms that act with deliberate speed, building regional regulatory fluency now, will find themselves holding durable partnerships, established project pipelines, and institutional credibility that late entrants will struggle to replicate at any price. In a region reshaping the global energy order, that positioning is worth considerably more than the compliance investment required to achieve it.