Mispriced and Misunderstood: Rebuilding the Valuation Framework for Asia-Pacific Utility Assets
A Valuation Problem Hiding in Plain Sight
In the years following the global financial crisis, yield-hungry US institutional investors discovered Asia-Pacific utility assets with considerable enthusiasm. Regulated networks in Australia, privatized distribution companies in the Philippines, and independent power producers across Southeast Asia all attracted capital from pension funds, infrastructure funds, and sovereign wealth vehicles seeking stable, long-duration returns.
Many of those investments have performed as expected. A meaningful number have not — and the underperformance, when examined carefully, traces back not to operational failures or market demand shortfalls, but to valuation errors made at the point of acquisition. Specifically, to the systematic underweighting of three interconnected risk categories: currency volatility, political and policy risk, and the ever-present possibility of regulatory reversal.
This is not a critique leveled at unsophisticated investors. Some of the most analytically rigorous infrastructure funds in the United States have made this mistake. The problem is structural: standard discounted cash flow models and comparable transaction analyses are built on assumptions calibrated to the relatively stable regulatory and macroeconomic environments of OECD markets. When those models are exported to Asia-Pacific without meaningful adjustment, they produce valuations that look defensible on a spreadsheet and prove costly in practice.
The Currency Dimension: More Complex Than a Hedge Ratio
The instinctive response to currency risk in cross-border infrastructure investment is to hedge it. In theory, this is straightforward. In practice, hedging long-duration utility cash flows denominated in Indonesian rupiah, Philippine pesos, or Vietnamese dong is neither cheap nor consistently available at the tenors that infrastructure investment requires.
Beyond the mechanics of hedging, currency risk in Asia-Pacific utility investments operates through channels that standard hedge ratios do not capture. Tariff structures in most regulated utility markets are set in local currency terms, and regulators in many jurisdictions have demonstrated a persistent reluctance to pass through currency-driven cost increases to end consumers. When the rupiah depreciates sharply against the dollar — as it did during the 2018 emerging market selloff and again during the COVID-driven volatility of 2020 — the real dollar value of a regulated utility's earnings can compress far more severely than the nominal exchange rate movement alone would suggest.
A more rigorous approach treats currency risk not as a financing overlay but as a fundamental input to the operating model. This means stress-testing tariff adequacy under depreciation scenarios, modeling the regulatory response to input cost inflation, and adjusting the terminal value assumption to reflect the probability that exit proceeds will be repatriated at an unfavorable rate relative to the entry exchange rate.
In practical terms, this often implies a discount rate adjustment of 150 to 300 basis points for utility assets in markets with managed or semi-managed exchange rate regimes, relative to comparable investments in freely floating currency environments.
Political Risk: Beyond the Binary
US investors frequently treat political risk as a binary variable — a country either has it or it doesn't, and the presence of political risk insurance from the Overseas Private Investment Corporation (now the DFC) is treated as adequate mitigation. This framing misses the more insidious forms of political risk that have most frequently damaged utility asset values across Asia-Pacific in recent years.
The most damaging political risk events in the region's utility sector have not been outright expropriation. They have been subtler: mid-contract tariff renegotiations initiated by newly elected governments seeking to demonstrate consumer protection credentials; changes to foreign ownership caps that force partial divestiture at below-market valuations; environmental permitting reversals that strand capital already committed to generation or transmission projects; and the selective enforcement of regulatory frameworks in ways that favor state-owned incumbents over private or foreign-owned competitors.
Pakistan's power sector provides an instructive recent example. International power producers who invested in the country's independent power producer framework during the 1990s and early 2000s faced protracted disputes over capacity payment arrears, with the government periodically threatening to renegotiate agreements it characterized as unfavorable to domestic consumers. The legal and operational costs of defending contractual positions consumed a substantial portion of the returns those investments were designed to generate.
A more calibrated approach to political risk assessment involves disaggregating the political environment into specific risk categories — expropriation, contract renegotiation, regulatory capture, and foreign exchange transfer restriction — and assigning probability-weighted discount rate adjustments to each. For markets with recent histories of mid-contract renegotiation, a premium of 100 to 200 basis points applied specifically to the contracted revenue stream is a defensible starting point.
Regulatory Reversal: The Risk That Looks Like Stability
Perhaps the most underappreciated valuation risk in Asia-Pacific utility investment is regulatory reversal — the unwinding of market liberalization frameworks that were implemented in prior political cycles and are subsequently modified or abandoned when the political calculus changes.
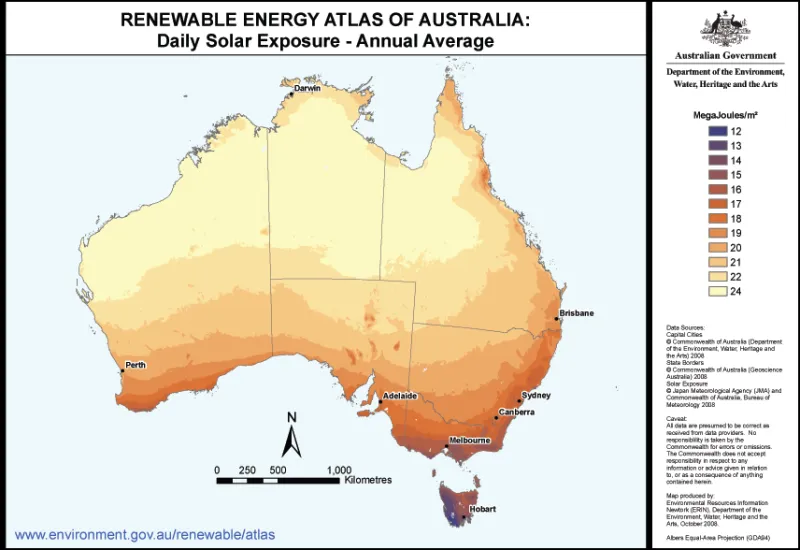
Australia's National Electricity Market has experienced multiple regulatory resets that altered the revenue profiles of network businesses in ways that were not fully anticipated in acquisition models. Hong Kong's electricity market, long characterized by its stable scheme of control framework, has faced increasing political pressure to restructure tariff-setting mechanisms and introduce competitive elements that would compress the returns available to the two incumbent franchised utilities.
For US investors, the key analytical discipline is to avoid treating regulatory stability as a permanent feature of markets where it has historically prevailed. A valuation framework that assigns zero probability to regulatory regime change over a 15- to 20-year investment horizon is not conservative — it is incomplete.
Building a More Honest Discount Rate
Pulling these risk dimensions together into a coherent valuation framework requires moving beyond the weighted average cost of capital models that dominate US infrastructure investment analysis. A jurisdiction-specific risk-adjusted framework for Asia-Pacific utility assets should incorporate explicit premium layers for currency duration risk, political risk by category, and regulatory reversal probability — each calibrated to the specific market, asset type, and investment tenor.
For US institutional investors who undertake this analytical work rigorously, the result is not uniformly higher discount rates and lower valuations. In some markets — Australia's regulated networks, Hong Kong's established utility franchises, Singapore's liberalized energy sector — a thorough risk decomposition will confirm that prevailing market valuations are broadly appropriate or even modestly attractive. In others, it will reveal that the headline yield on an apparent bargain acquisition conceals risk-adjusted returns that are materially inferior to what comparable capital could earn in domestic markets.
The goal is not to make Asia-Pacific utility investment look less attractive. It is to make the analysis honest enough that when US investors do commit capital to the region, they do so with a clear-eyed understanding of what they are actually buying.